Key Takeaways
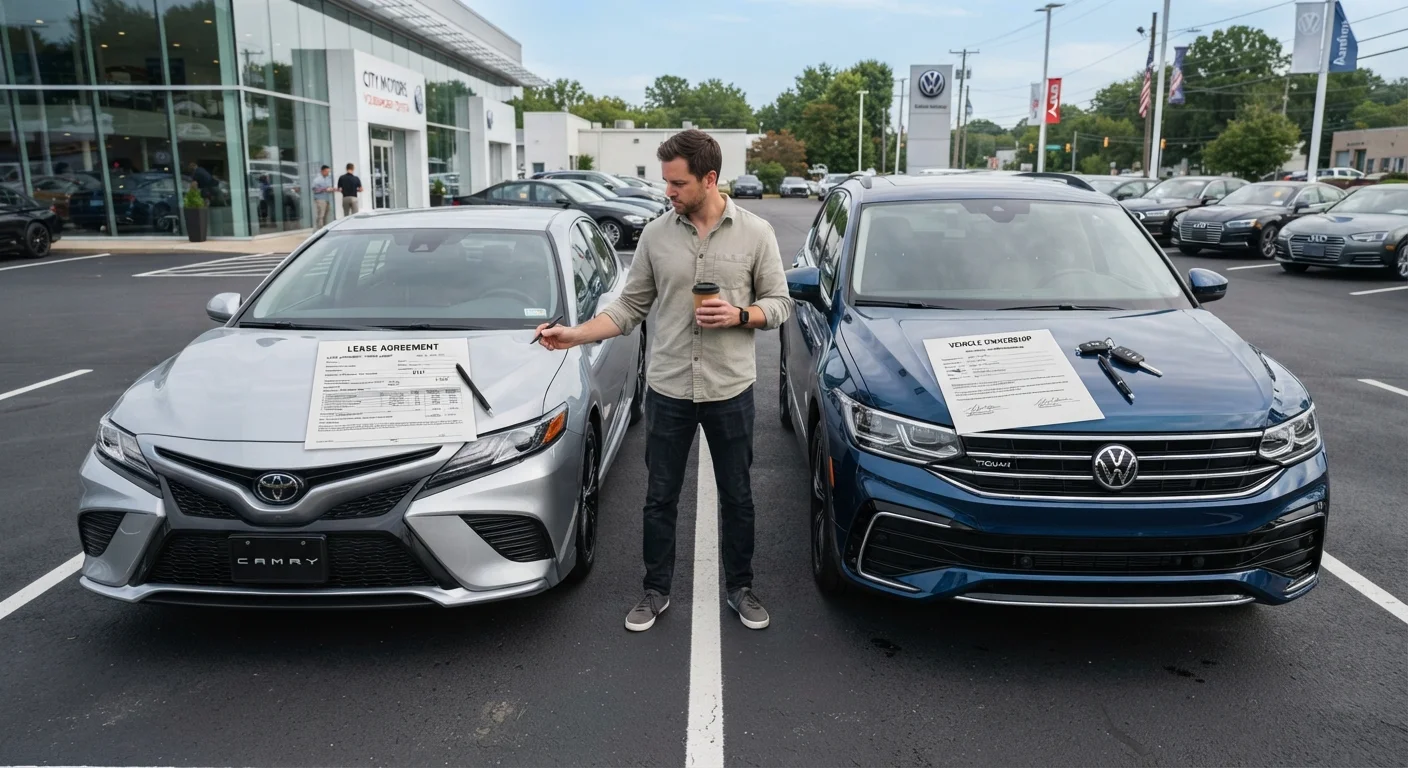
- A lease is essentially a long-term rental: you pay for depreciation, not the full vehicle value.
- Buying means financing or paying the entire vehicle price, then owning it outright once the loan is cleared.
- Monthly lease payments are typically lower than loan payments for the same vehicle.
- Leases carry mileage limits and condition fees that can add costs at the end of the contract.
- Buyers build equity over time, which can offset future vehicle costs through trade-in or resale.
- Neither option is universally cheaper; total cost depends on how long you keep the car and how you use it.
Option A
Leasing a car
The lower monthly cost, no long-term ownership path.
Best for: Households that want predictable payments, prefer driving newer vehicles every few years, and drive within defined annual mileage limits.
Option B
Buying a car
The full ownership path with long-term equity.
Best for: Families who drive high mileage, want to build equity, or plan to keep a vehicle well beyond the loan payoff date.
If your household drives more than 15,000 miles per year
Buying a car
Lease contracts typically cap annual mileage at 10,000 to 15,000 miles, with per-mile overage fees that add up quickly for high-mileage drivers.
If you want the lowest possible monthly payment for a late-model vehicle
Leasing a car
Because lease payments cover depreciation rather than the full purchase price, they are generally lower than loan payments for an equivalent vehicle.
If you plan to keep your vehicle for seven or more years
Buying a car
Once a loan is paid off, ownership continues at zero monthly cost, making buying more economical the longer you hold the vehicle.
If predictable, warranty-covered expenses are your priority
Leasing a car
Most lease terms align with the manufacturer warranty period, so major mechanical costs are less likely during the lease cycle.
If building long-term household net worth matters to your budget planning
Buying a car
A purchased vehicle is an asset with resale or trade-in value, even accounting for depreciation, while a lease leaves no equity at contract end.
How the financial structure of leasing works
When you lease a car, you are paying for the portion of the vehicle's value that you consume during the lease term, not the car itself. The dealer and manufacturer calculate this as the difference between the vehicle's capitalized cost (essentially the agreed purchase price) and its estimated residual value (what the car is projected to be worth at lease end).
That depreciation amount, spread across the lease term, forms the core of your monthly payment. A money factor, which functions like an interest rate, is applied on top to cover financing costs. The money factor is usually expressed as a small decimal (for example, 0.00125), and multiplying it by 2,400 converts it to an approximate annual percentage rate.
Because you are only financing depreciation rather than the full vehicle price, monthly payments on a lease are almost always lower than loan payments for the same car. However, several costs can accumulate beyond the monthly figure:
- Acquisition fees charged at lease signing
- Per-mile charges for exceeding the contract mileage allowance
- Disposition fees at lease end if you do not buy the vehicle
- Excess wear-and-tear charges assessed during the return inspection
Before signing any lease contract, a careful review of these terms is worth your time. This checklist covers the key contract terms to examine before you commit, including mileage caps and money factors.
How the financial structure of buying works
Buying a car means paying its full purchase price, either upfront in cash or through an auto loan. With a loan, a lender advances the purchase amount, and you repay principal plus interest over a fixed term, typically 24 to 84 months.
The annual percentage rate (APR) on an auto loan is the true cost of that borrowing. A lower APR or shorter loan term reduces total interest paid, even if the monthly payment is higher. Understanding how APR, loan length, and down payments interact helps families compare loan offers accurately before committing.
Once the loan is paid off, ownership continues at no monthly cost, which is where buying tends to outperform leasing over a long holding period. The vehicle also carries resale or trade-in value that partially offsets what you paid. That value erodes over time through depreciation, but it never drops to zero the way a lease's return-with-nothing arrangement does.
| Criterion | Leasing | Buying |
|---|---|---|
| What you pay for | Depreciation during lease term | Full vehicle purchase price |
| Monthly payment (same vehicle) | Generally lower | Generally higher |
| Ownership at end of term | None (unless buyout exercised) | Full ownership |
| Equity built | Zero | Resale or trade-in value |
| Mileage flexibility | Capped, overage fees apply | Unlimited |
| Maintenance risk | Low (within warranty period) | Higher after warranty ends |
| Long-term cost (7+ years) | Higher (repeated contracts) | Lower (zero payment after payoff) |
| Flexibility to modify vehicle | Very limited | Full discretion |
Cash purchases eliminate interest entirely, though they tie up a lump sum that could otherwise stay in savings or investments. The trade-offs between auto loans and cash purchases go beyond the sticker price and are worth considering as a household budget decision.
Where the real cost differences appear
Comparing monthly payments alone gives a misleading picture. The clearer comparison runs across the full period you plan to use a vehicle.
Over a short horizon, such as three to four years, leasing often costs less in total outlays because payments are lower and the consumer absorbs only depreciation. A buyer in the same period is still deep into repaying principal and interest on a loan.
Over a longer horizon, the math shifts. A buyer who keeps a vehicle for eight years pays off the loan partway through and then drives at no monthly cost. A serial lessee restarts payments with every new contract. A detailed comparison of long-term costs for buyers and lessees shows how this gap widens depending on vehicle choice and contract terms.
Two other factors commonly shift the comparison for families:
- Mileage: Households driving 18,000 or more miles per year typically face significant overage fees under a standard lease, which close or reverse any monthly payment advantage.
- Vehicle condition: Buyers who carry their cars past the warranty period absorb repair costs directly. Lessees avoid that risk during the lease cycle but also build no equity to offset future vehicle costs.
New and used vehicle depreciation curves also affect this calculation because a new car loses value fastest in its first few years, which is exactly the period a lease covers.
This article is for general informational purposes only and does not constitute financial or legal advice. Consult a qualified financial professional for guidance specific to your situation.