Key Takeaways
- APR, not just the interest rate, is the number to compare across loan offers.
- A longer loan term lowers your monthly payment but increases total interest paid.
- Your credit score is one of the strongest factors shaping the rate a lender offers.
- A larger down payment reduces the principal, which directly reduces total interest.
- Monthly payment size alone does not reveal whether a loan is affordable or costly.
Auto loan interest
Auto loan interest is the fee a lender charges you for borrowing money to buy a vehicle. It is calculated as a percentage of the loan balance and added to your monthly payments over the life of the loan. The higher the rate or the longer the term, the more you pay in total above the vehicle's purchase price.
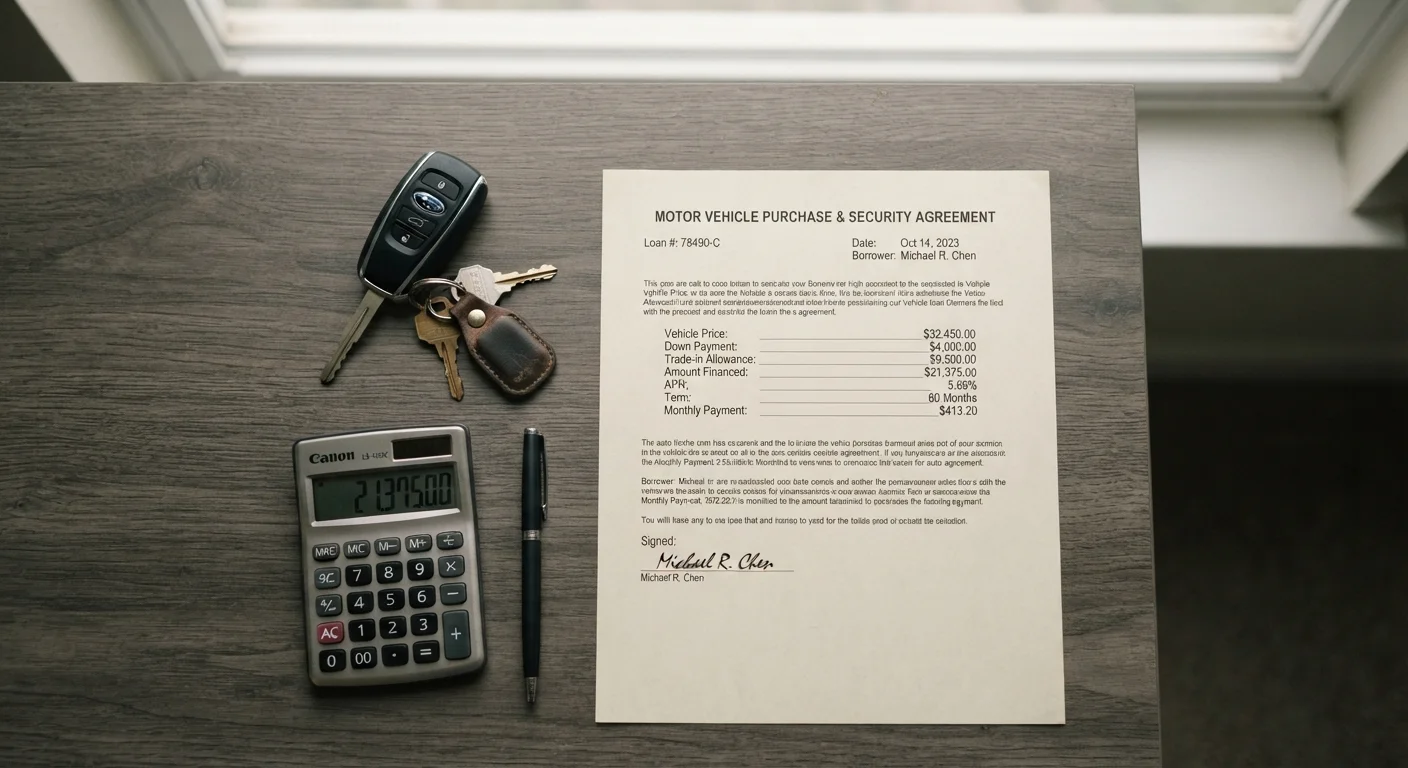
Most auto loans use simple interest, meaning interest accrues daily on the outstanding principal balance rather than compounding. The Annual Percentage Rate (APR) includes both the interest rate and any lender fees, making it the more accurate figure for comparing loan offers.
How interest accumulates on a car loan
When a lender provides an auto loan, it charges interest on the amount you borrowed, called the principal. For most U.S. auto loans, that interest is calculated daily using the simple interest method: divide the annual rate by 365, multiply by the current principal balance, and you have one day's interest charge.
Because interest accrues on the remaining balance, your early payments carry a higher interest portion. As you pay down the principal each month, the interest share of each payment shrinks and the principal share grows. This pattern is called amortization. A loan amortization schedule shows exactly how each payment is split between interest and principal across every month of the term.
This structure has a practical consequence: if you make only minimum payments, a significant share of your early dollars goes to the lender rather than toward the vehicle. Understanding how APR, term length, and down payments interact before you borrow helps you see the full cost rather than just the monthly number.
~$1,900
Extra interest on a 72-month vs. 48-month loan
Based on a $25,000 loan at 7% APR, illustrating how term length alone changes total cost.
$7,800
Total interest for a subprime borrower on a $20,000 loan
Compared to roughly $3,400 for a borrower with good credit on identical 60-month, $20,000 terms at 14% vs. 6.5% APR.
36-84
Typical auto loan term range in months
The Consumer Financial Protection Bureau notes that terms beyond 60 months increase the risk of negative equity.
What APR actually tells you
APR (Annual Percentage Rate) is the most useful single figure for comparing auto loan offers. It combines the stated interest rate with any origination fees or finance charges the lender folds into the loan, then expresses the total as an annual percentage. Two loans with an identical stated rate can have different APRs if one includes higher fees.
Lenders are required by federal law under the Truth in Lending Act (TILA) to disclose APR before you sign. When comparing offers, use APR rather than the monthly payment or the stated rate alone. A loan with a slightly higher APR will cost more in total, even if the monthly difference looks small.
A low monthly payment can mask a costly loan when the APR is high or the term is long. Focus on total interest paid over the full term, not just what fits your monthly budget today.
How loan term length changes your total cost
Loan term is the number of months you have to repay the loan. Common terms run from 36 to 84 months. A shorter term means higher monthly payments but less total interest. A longer term reduces the monthly payment but extends the period during which interest accumulates.
Consider a $25,000 loan at 7% APR. Over 48 months the total interest paid would be roughly $3,700. Extend that same loan to 72 months and total interest climbs to around $5,600, a difference of nearly $1,900 for the same vehicle at the same rate. Longer terms also increase the risk of becoming "upside down" on the loan, meaning the outstanding balance exceeds the vehicle's market value. Vehicles depreciate quickly in the first few years, which makes this gap a real financial risk if the vehicle is totaled or needs to be sold early.
For context on what to check before signing any vehicle contract, term length and prepayment rules are two of the most consequential details.
The factors lenders use to set your rate
No single universal rate applies to all borrowers. Lenders set individual rates based on several variables assessed at application.
- Credit score: borrowers with higher scores typically receive lower rates because they present lower repayment risk to the lender.
- Loan-to-value ratio: financing a smaller percentage of the vehicle's value (by making a larger down payment) can improve the rate offered.
- Loan term: longer terms sometimes carry higher rates because the lender's risk exposure extends over more time.
- Vehicle age: new vehicles often qualify for lower rates than used vehicles, partly because their value is more predictable.
- Lender type: banks, credit unions, and dealership finance arms each price loans differently. Credit unions frequently offer lower rates to their members than other lender types, though this varies.
Auto loan interest is general financial information, not personalized advice. A licensed financial professional can help you evaluate what loan structure fits your specific situation. See also the full picture of vehicle ownership costs, which extend well beyond the loan itself.
Get pre-approved before visiting a dealer
Securing a rate offer from a bank or credit union before shopping gives you a concrete number to compare against any financing a dealership presents. Dealers often have flexibility in the rates they offer, and a competing offer gives you a benchmark. Pre-approval does not obligate you to use that lender.
Strategies that reduce total interest paid
Several approaches can reduce the total interest a borrower pays without requiring a perfect credit score or a large cash reserve.
A larger down payment reduces the principal from day one, which directly reduces the base on which interest is calculated. Even an extra $1,000 up front produces measurable savings over the loan term. Making additional principal payments during the loan accomplishes the same thing over time: each extra dollar applied to principal is a dollar on which no future interest accrues.
Shopping multiple lenders before accepting any offer gives you a basis for comparison. Pre-approval from a credit union or bank before visiting a dealership gives you a concrete benchmark rate to compare against dealer financing. Financing and paying cash each carry real trade-offs that depend on your full financial picture, so evaluating both paths is worthwhile before committing.
This article is for general informational and educational purposes only and does not constitute financial or lending advice. Consult a qualified financial professional before making borrowing decisions.