Key Takeaways
- Travel credit cards can generate meaningful rewards, but only if the card's annual fee is offset by benefits you actually use.
- Sign-up bonus spending minimums can pressure families into charging more than they planned.
- Rewards point values vary widely depending on how and when you redeem them.
- Families who pay balances in full each month get the most from travel cards; those who carry balances typically lose money.
- Free checked bags and lounge access add up, but only for families who fly frequently with the issuing airline.
Checked bag waivers cover annual fees in one trip
A family of four checking bags round-trip can save $200 to $300 per flight in airline fees, often exceeding the card's annual cost before any points are redeemed.
Sign-up bonuses provide a large initial rewards deposit
Many travel cards offer bonuses worth $500 or more in travel after meeting an initial spending minimum, which can cover a meaningful portion of a family trip.
Earning rewards on everyday spending
Families with high monthly grocery, gas, and utility bills accumulate points passively without changing spending behavior, accelerating reward balances over time.
Built-in travel protections reduce out-of-pocket risk
Trip delay insurance, lost baggage reimbursement, and rental car coverage bundled with many cards can replace separate travel insurance purchases that families might otherwise buy.
Annual travel credits offset the stated fee
Some cards issue $100 to $300 in annual travel credits that apply automatically to airline purchases or hotel bookings, reducing the effective cost of holding the card.
High annual fees require consistent, high-value redemptions
Premium travel cards charge $400 to $550 annually. Families who do not fly frequently enough to use lounge access, elite status perks, or multiple travel credits will pay more than they recover.
Spending minimums for bonuses can encourage overspending
A sign-up bonus requiring $4,000 in spending within three months can push families to charge purchases they had not budgeted for, negating the bonus's financial benefit.
Interest charges erase rewards for families carrying balances
Travel cards commonly carry APRs above 20%. A single month of carrying a $2,000 balance can cost more in interest than several months of accumulated points are worth.
Award availability is limited during school holiday windows
Families must travel during peak periods when children are out of school, which is precisely when airlines and hotels hold back award inventory or require more points per redemption.
Point values fluctuate and devalue over time
Card issuers and airline programs can change redemption rates with little notice, reducing the value of accumulated balances that families may have been saving for a specific trip.
Our Verdict
Travel credit cards can genuinely reduce what families pay for flights and hotels, but only under specific conditions: balances paid in full every month, enough annual travel to absorb the annual fee, and a consistent enough spending pattern to accumulate rewards at a useful pace. For families who carry balances or travel infrequently, the interest charges and unused perks will outweigh any rewards earned.
Families who pay their card balance in full each month, fly at least two or three times a year, and spend enough annually to exceed the card's fee through redeemable rewards.
How travel credit cards work for families
Travel credit cards earn points or miles on purchases, which can then be redeemed for flights, hotel stays, or other travel costs. Most cards also carry perks such as free checked bags, priority boarding, or airport lounge access. Some issue a travel credit each year that offsets the annual fee directly.
For families, the appeal is straightforward: a trip that costs $3,000 in flights and hotels might be partially or fully covered by accumulated rewards. The math, however, depends on how much the family spends, how they redeem, and whether the card's ongoing costs stay below the value they extract. Before picking a card, it helps to build a realistic travel budget so you know what you are actually trying to offset.
Checked bag waivers cover annual fees in one trip
A family of four checking bags round-trip can save $200 to $300 per flight in airline fees, often exceeding the card's annual cost before any points are redeemed.
Sign-up bonuses provide a large initial rewards deposit
Many travel cards offer bonuses worth $500 or more in travel after meeting an initial spending minimum, which can cover a meaningful portion of a family trip.
Earning rewards on everyday spending
Families with high monthly grocery, gas, and utility bills accumulate points passively without changing spending behavior, accelerating reward balances over time.
Built-in travel protections reduce out-of-pocket risk
Trip delay insurance, lost baggage reimbursement, and rental car coverage bundled with many cards can replace separate travel insurance purchases that families might otherwise buy.
Annual travel credits offset the stated fee
Some cards issue $100 to $300 in annual travel credits that apply automatically to airline purchases or hotel bookings, reducing the effective cost of holding the card.
The real costs families often underestimate
Annual fees on travel cards commonly run from $95 to $550 or more. A family must extract at least that much in usable value each year just to break even. That calculation gets harder when the card's top perks, like airport lounges or hotel elite status, go unused.
Sign-up bonuses are where many families first get interested. A bonus worth several hundred dollars in travel sounds compelling, but earning it usually requires spending a set minimum within the first three to four months. Families who charge ordinary expenses like groceries and utilities to hit that threshold may do fine. Those who feel pressure to overspend to reach the minimum are paying for rewards with money they would not have spent otherwise.
Interest is the bigger trap. Travel cards tend to carry higher annual percentage rates than basic credit cards. Any month a family carries a balance, interest charges can erase weeks of accumulated rewards.
High annual fees require consistent, high-value redemptions
Premium travel cards charge $400 to $550 annually. Families who do not fly frequently enough to use lounge access, elite status perks, or multiple travel credits will pay more than they recover.
Spending minimums for bonuses can encourage overspending
A sign-up bonus requiring $4,000 in spending within three months can push families to charge purchases they had not budgeted for, negating the bonus's financial benefit.
Interest charges erase rewards for families carrying balances
Travel cards commonly carry APRs above 20%. A single month of carrying a $2,000 balance can cost more in interest than several months of accumulated points are worth.
Award availability is limited during school holiday windows
Families must travel during peak periods when children are out of school, which is precisely when airlines and hotels hold back award inventory or require more points per redemption.
Point values fluctuate and devalue over time
Card issuers and airline programs can change redemption rates with little notice, reducing the value of accumulated balances that families may have been saving for a specific trip.
Points and miles: what the value actually looks like
Points and miles are not a fixed currency. One airline mile might be worth less than a cent when redeemed for a domestic coach seat, or considerably more when used for a business-class international ticket. Hotel points tend to deliver more consistent value for standard redemptions, but blackout dates and category caps limit flexibility.
Families traveling with children face a specific constraint: award seats and award hotel rooms must be available in sufficient quantity for the whole group at the same time. Availability is often limited, particularly during school holiday windows when most families need to travel.
Award availability and family travel windows
Most families need to travel during summer, spring break, or major holidays when children are out of school. Award seat and room availability is generally lower during these periods, and programs often require more points per redemption. Booking award travel six to eleven months in advance, when availability first opens, gives families the widest selection before peak inventory is claimed.
Pairing a travel card with flexible scheduling can improve award availability. Families who can shift by even a few days often find more options. Flexible travel dates unlock lower fares in cash bookings and can open up award space as well.
When perks translate to real savings
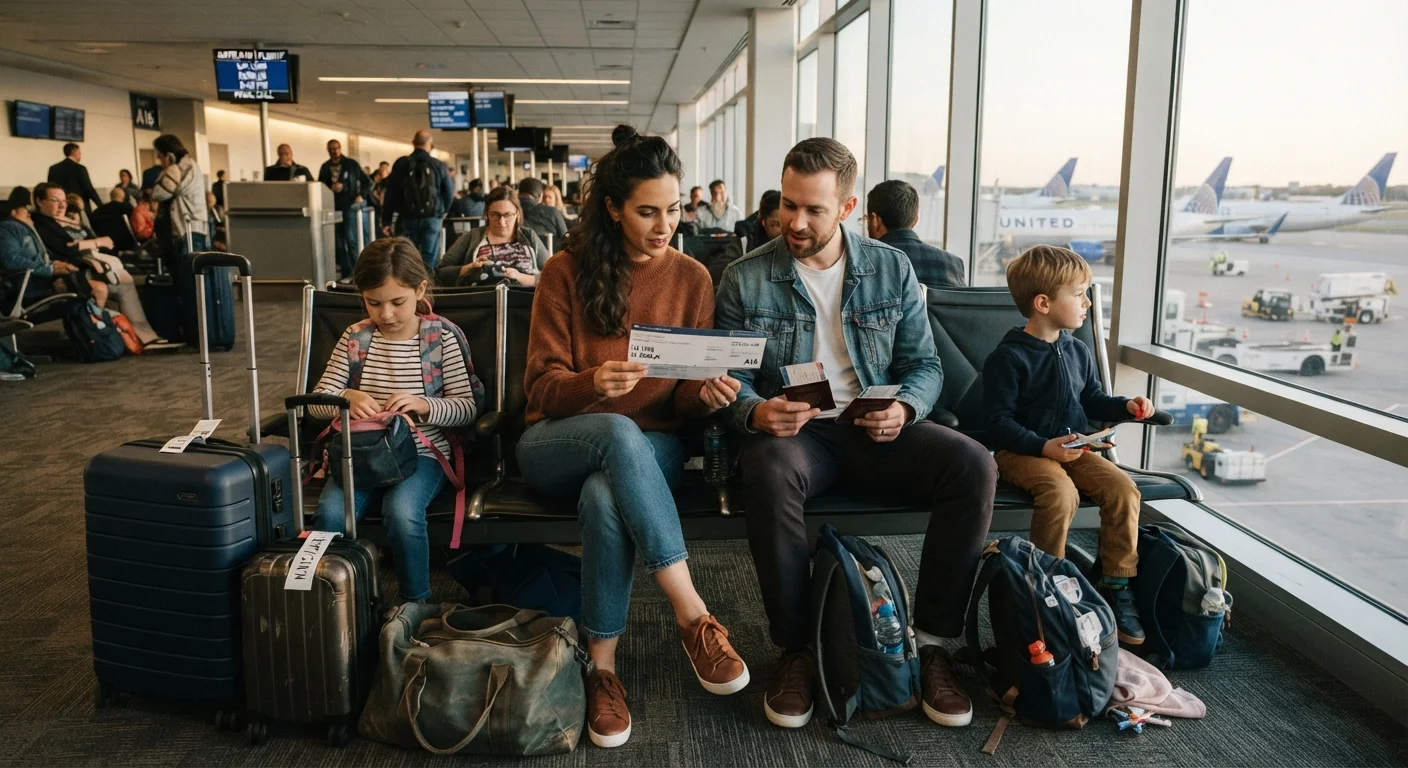
Checked bag waivers are among the most concrete benefits for families. Airlines commonly charge $35 or more per bag each way. A family of four checking two bags on a round trip could save $280 per flight, which covers or exceeds many cards' annual fees in a single trip.
Travel insurance bundled with many cards, covering trip cancellation, delay reimbursement, and lost baggage, has real dollar value that families often discover only after something goes wrong. Reading the coverage terms before a trip is worth the time.
For families who travel frequently and consider both loyalty programs and direct booking options, a broader comparison is useful. Loyalty programs versus discount travel sites covers how each approach performs for budget-conscious families.
$35+
Typical airline checked bag fee per bag, each way
Per-bag fees published by major U.S. carriers make a four-person family's round-trip bag costs one of the most easily quantified card benefits.
20%+
Common APR range on travel credit cards
The Consumer Financial Protection Bureau has reported that rewards cards, including travel cards, tend to carry higher interest rates than non-rewards cards.
$95-$550
Typical annual fee range for travel credit cards
The gap between entry-level and premium travel cards is wide; families should calculate usable benefit value before choosing a tier.
A straightforward way to decide
The clearest test is simple arithmetic. Add up the card's annual fee, then list every perk you will realistically use in the next 12 months and assign a dollar value to each. If the perk total exceeds the fee, the card is worth holding. If it does not, a no-fee card or a cash-back card that earns a flat rate on all purchases may leave more money in the household budget.
Families who travel off-peak to reduce base costs can find that travel cards compound those savings. Shoulder season travel lowers the cash price of flights and hotels, and applying points to an already-reduced fare stretches redemption value further. Where you stay also affects the math: vacation rentals versus hotels is a separate decision that interacts with which card's rewards are most useful.