Key Takeaways
- The sticker price and monthly payment rarely capture the full annual cost of owning a vehicle.
- Registration fees, sales tax, and title charges vary widely by state and can add hundreds to thousands at purchase.
- Gap insurance, tire replacement, and routine maintenance are recurring costs families frequently underestimate.
- Depreciation affects resale value and loan balance, which matters if you sell or trade in before the loan ends.
- Building a realistic total-cost estimate before committing to a vehicle prevents budget shortfalls later.
Why the purchase price is only part of the picture
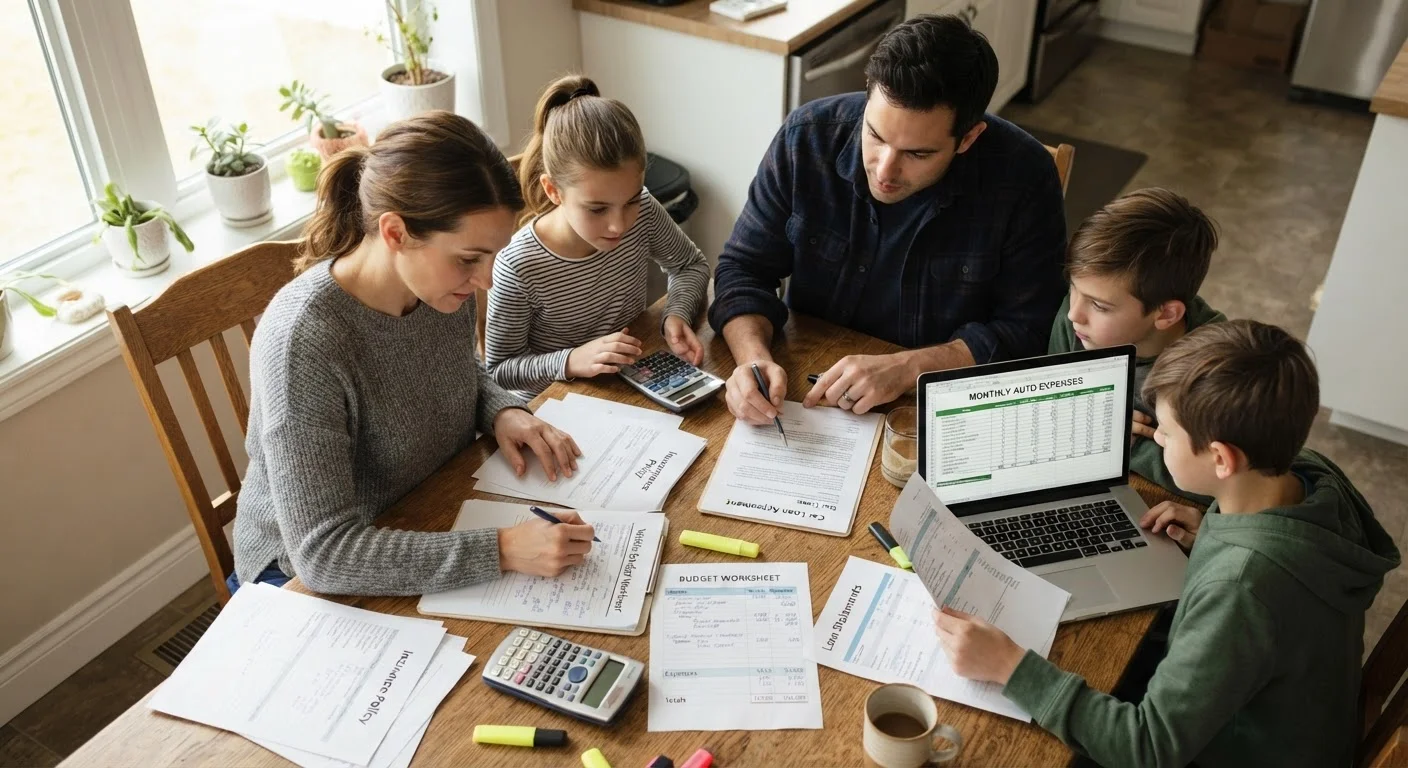
Families often anchor their vehicle budget to one number: the monthly payment. That number feels manageable, so the deal gets done. The problem is that a monthly payment reflects only the loan, not the full cost of ownership. The true affordability of a vehicle includes insurance, fuel, maintenance, fees, and taxes, most of which are due before or shortly after you drive off the lot.
For a household watching its budget carefully, the gap between the payment and the real annual outlay can be significant. The sections below cover the costs that catch families off guard most often, and what to do about each one.
Ignoring state registration fees, title charges, and sales tax at purchase.
Why it happens: Shoppers focus on the negotiated vehicle price and overlook the government fees added at closing. These vary considerably by state and are due upfront, not spread across the loan in most cases.
Skipping gap insurance on a financed vehicle with a small down payment.
Why it happens: Gap insurance (Guaranteed Asset Protection) covers the difference between what you owe on a loan and what the insurer pays if the car is totaled. Buyers either do not know it exists or assume standard comprehensive coverage handles the full loan balance.
Underestimating how fast a new vehicle depreciates.
Why it happens: Most buyers think of depreciation as a distant resale concern rather than an immediate financial factor. In practice, a new vehicle can lose a substantial portion of its value within the first few years, which matters if you plan to sell or trade in before the loan ends.
Forgetting to account for insurance cost increases after purchase.
Why it happens: Families often check their current insurance rate but do not get a revised quote for the specific make, model, and trim they are about to buy. A larger or newer vehicle typically costs more to insure than the one being replaced.
Treating the loan agreement as a formality rather than a binding financial document.
Why it happens: After hours at a dealership, most buyers sign the financing paperwork quickly without reading it closely. Prepayment penalties, extended warranty add-ons, and dealer-installed accessories can all appear in the contract without explicit discussion.
Ongoing costs that require their own budget line
Once the purchase costs are settled, a separate set of recurring expenses begins. Routine maintenance is the most predictable of these. Oil changes, tire rotations, brake pads, and filters follow manufacturer-recommended intervals and add up steadily over a year. The annual cost of routine maintenance for a typical family vehicle is often higher than owners expect, particularly for trucks and SUVs with more complex service schedules.
Tires are a separate line item many families forget entirely until a set wears out. A full set of replacement tires for a midsize SUV can run several hundred dollars, and all-season or winter-specific tires cost more. Setting aside a small amount monthly into a dedicated vehicle fund smooths out these lumpy expenses when they arrive.
Tire and brake costs arrive without warning
Tires and brakes wear on their own schedule, not yours. A vehicle that passes its pre-purchase inspection can still need new tires or brake pads within the first year of your ownership, particularly if the previous owner deferred maintenance. Factor a tire and brake reserve into your vehicle budget from the start, rather than treating these as surprise expenses. For a practical schedule, the owner's manual maintenance guide outlines when these components typically need attention.
Fuel costs also shift with driving patterns. A vehicle that works for a short commute may cost considerably more to run when the family adds a school route, weekend activities, or longer errands. Running a realistic monthly mileage estimate before purchase gives a clearer fuel-cost figure than the EPA rating alone.
For families considering whether to finance or pay cash, the trade-offs between a loan and a cash purchase affect how these ongoing costs interact with the household budget overall.